


Japan recorded a 1.01 trillion yen ($6.2 billion) trade deficit during the first half of 2026, according to preliminary government data. This does not mean that Japan will collapse tomorrow, but it is another crack in the foundation of a debt structure that can no longer withstand rising interest rates, a collapsing currency, and imported inflation.
Japan’s exports increased 13.7% during the first six months of the year to 60.66 trillion yen. Imports rose 10.7% to around 61.9 trillion yen. Yet Japan still imported more than it exported despite a yen so weak that Japanese products should be extremely competitive abroad.
The June figures reveal exports rose 19.3% year-over-year, marking the tenth consecutive monthly increase. Imports, however, surged 25.4% to a record 11.3 trillion yen. That left Japan with a 406.9 billion yen deficit for June, more than three times the 120 billion yen shortfall economists had expected. Japan had recorded a 122 billion yen surplus during June 2025.
Japan depends heavily on imported energy. The conflict with Iran and disruptions around the Strait of Hormuz have raised the cost of oil while forcing Japan to seek supplies from more distant sources. Japan’s oil import volume actually declined 13.7% in June, but the value of those imports increased 59.3%. Japan bought less oil and paid far more for it.
That is the consequence of a weak currency colliding with an external energy shock. The yen has fallen beyond 163 to the dollar, its weakest level since 1986. It stood near 140 a year earlier. Every barrel of oil, shipment of natural gas, imported food product, and foreign industrial component becomes more expensive when priced in yen.
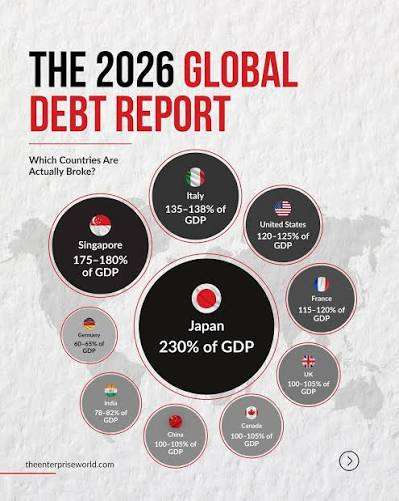
Japan accumulated the largest sovereign debt burden in the industrialized world while interest rates were held artificially near zero. Government debt exceeds 200% of GDP by virtually every major international estimate, while broader measurements place the burden above 230%. Politicians convinced themselves that the debt did not matter because Japanese institutions held most of it and the Bank of Japan could always purchase whatever the private market rejected.
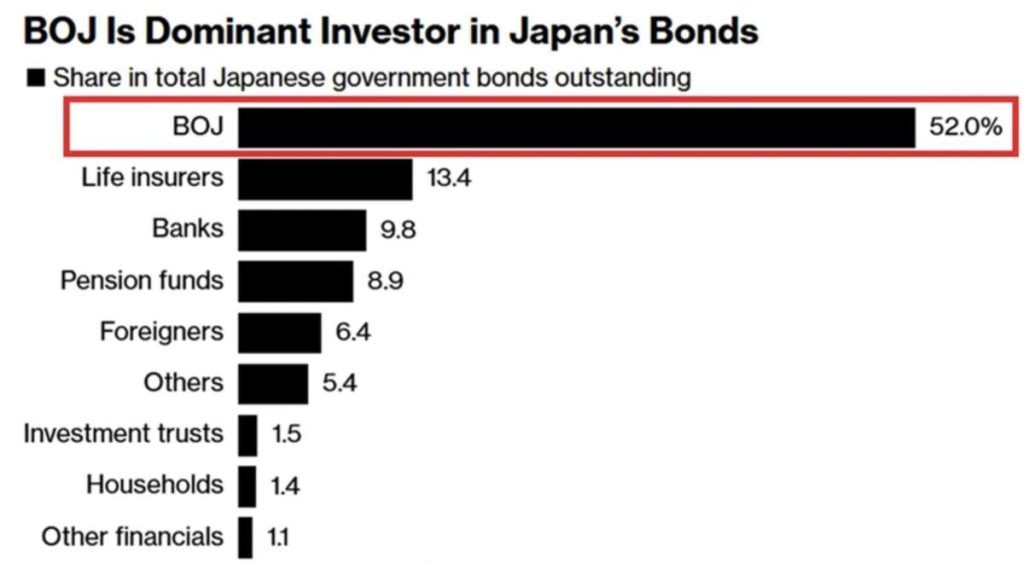
The Bank of Japan held approximately 485.4 trillion yen in Japanese government bonds as of March 2026, representing 47.9% of outstanding JGBs under the government’s calculation. This is not a free market. The central bank became the market because the government could not have financed this mountain of debt at normal interest rates. That arrangement worked only while inflation remained subdued and the yen retained public confidence. Both conditions are now breaking down.
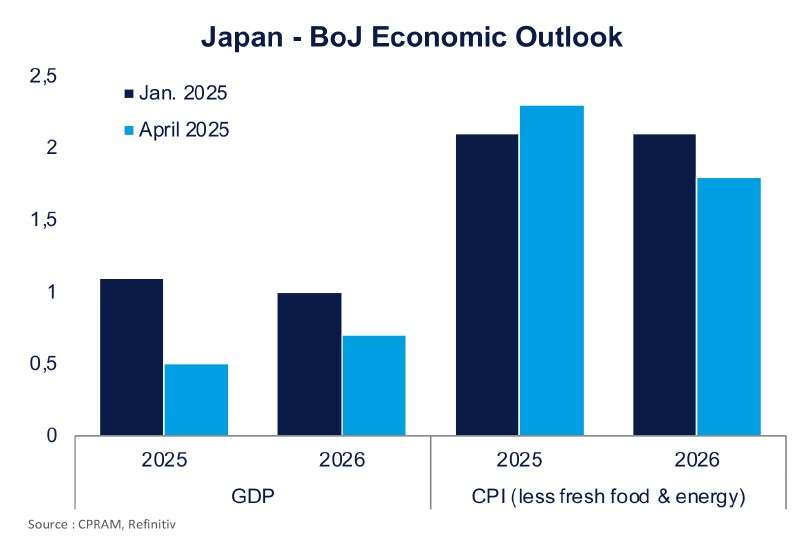
The Bank of Japan raised its policy rate to 1% in June, the highest level in 31 years. Under ordinary circumstances, raising rates would help support the currency and contain inflation. Japan is not operating under ordinary circumstances. Every increase in rates gradually raises the government’s cost of refinancing debt that was accumulated under zero-rate policies.
Japan’s fiscal 2026 budget totals a record 122.3 trillion yen. Debt-service expenditures, including interest and redemptions, have jumped 10.8% to 31.3 trillion yen. That means more than one-quarter of general government spending is already being consumed by past borrowing.
The Finance Ministry estimates that debt-service costs could reach 40.3 trillion yen by fiscal 2029, representing roughly 30% of total government expenditures. Annual bond issuance is projected to rise 28% from its 2026 level to around 38 trillion yen by that time. The government will be issuing additional debt primarily because servicing the existing debt is becoming more expensive.
That is the sovereign debt spiral. New bonds must be issued to pay the interest and redeem the old bonds. As rates rise, the government requires still more borrowing. As borrowing increases, investors demand higher yields to compensate for fiscal and currency risk. The process feeds upon itself.
Japan’s 10-year government bond yield reached approximately 2.74% on July 22, more than one percentage point above where it stood a year earlier. Japan constructed its fiscal system around rates close to zero. A yield of 2.74% may look insignificant to an American investor who remembers much higher Treasury yields, but that comparison is meaningless. The danger depends on the size of the debt relative to the government’s tax base, not simply the nominal interest rate.
The Bank of Japan is trapped. If it raises rates aggressively to defend the yen, it increases government debt-service costs and inflicts losses on banks, insurers, pension funds, and other institutions holding government bonds. If it keeps rates too low, capital continues to move away from the yen, the currency declines, and imported inflation accelerates. If it resumes massive bond purchases, it confirms that the debt cannot be financed naturally and further undermines confidence in the currency.
Tokyo has already spent an estimated $215 billion intervening in currency markets, yet the yen has still fallen to a 40-year low. Currency intervention cannot repair a structural fiscal imbalance. A government can buy its currency temporarily, but it cannot force global capital to trust policies that no longer make sense.
Japan can no longer defend the currency without threatening the bond market, support the bond market without weakening the currency, subsidize energy without issuing more debt, or raise taxes without damaging an already strained population. Japan’s aging population makes the situation even worse. The tax base is shrinking while pension, medical, and social-service obligations increase. Social-security expenditures in the fiscal 2026 budget reached approximately 39.1 trillion yen. Debt service and social security together consume an enormous portion of government spending before politicians fund defense, infrastructure, education, energy subsidies, or anything else.
The $6.2 billion trade deficit is modest compared with Japan’s total economy, and by itself it is not a sovereign default signal. Anyone claiming that one trade report proves Japan is bankrupt is exaggerating. The importance of this report is that it shows the mechanism tightening: war raises energy prices, the weak yen magnifies those prices, imports overwhelm export growth, inflation pressures the Bank of Japan to raise rates, and higher rates increase the cost of servicing the world’s largest developed-market debt burden.
Japan is the first domino because it pushed modern monetary experimentation further than any other major economy. It normalized zero and negative interest rates, allowed its central bank to dominate the government bond market, and assumed domestic savings would finance public deficits forever. Europe and the United States followed the same path later, believing they could avoid Japan’s fate.
Fitch now projects that developed-market government debt will reach a record $75.8 trillion by the end of 2026, equal to 104% of global GDP. The ten largest developed economies will account for $69 trillion of that total. Japan may remain the most extreme example, but it is not an isolated case.
The Japanese trade deficit is another warning shot. The sovereign debt crisis will not necessarily begin with a formal announcement from the Ministry of Finance. It will begin through currency weakness, failed interventions, rising bond yields, imported inflation, captive domestic capital, and an increasing share of tax revenue diverted toward interest payments.
Japan is not merely experiencing a weak yen or a temporary energy problem. It is approaching the point where every available policy creates another crisis somewhere else. That is how confidence begins to fracture, and once confidence turns against government debt, no central bank can restore it by simply creating more money.
Read the full article here